
ProfessorSovereign: Finance
Deterministic MCTS macroeconomic liquidity wargaming, ISDA CSA margin squeeze simulation, and continuous SEC EDGAR corporate debt covenant radar.
Deterministic Early Warning System • Continuous ISDA, Covenant & OFAC Sieve
The Deterministic Time Machine: Historical MCTS Post-Mortems
Mathematical proof that our deterministic MCTS engine would have caught the three greatest financial crashes in modern history long before the market reacted. Narrated by Chris Martin with cryptographic SR 11-7 Merkle root audit proofs.
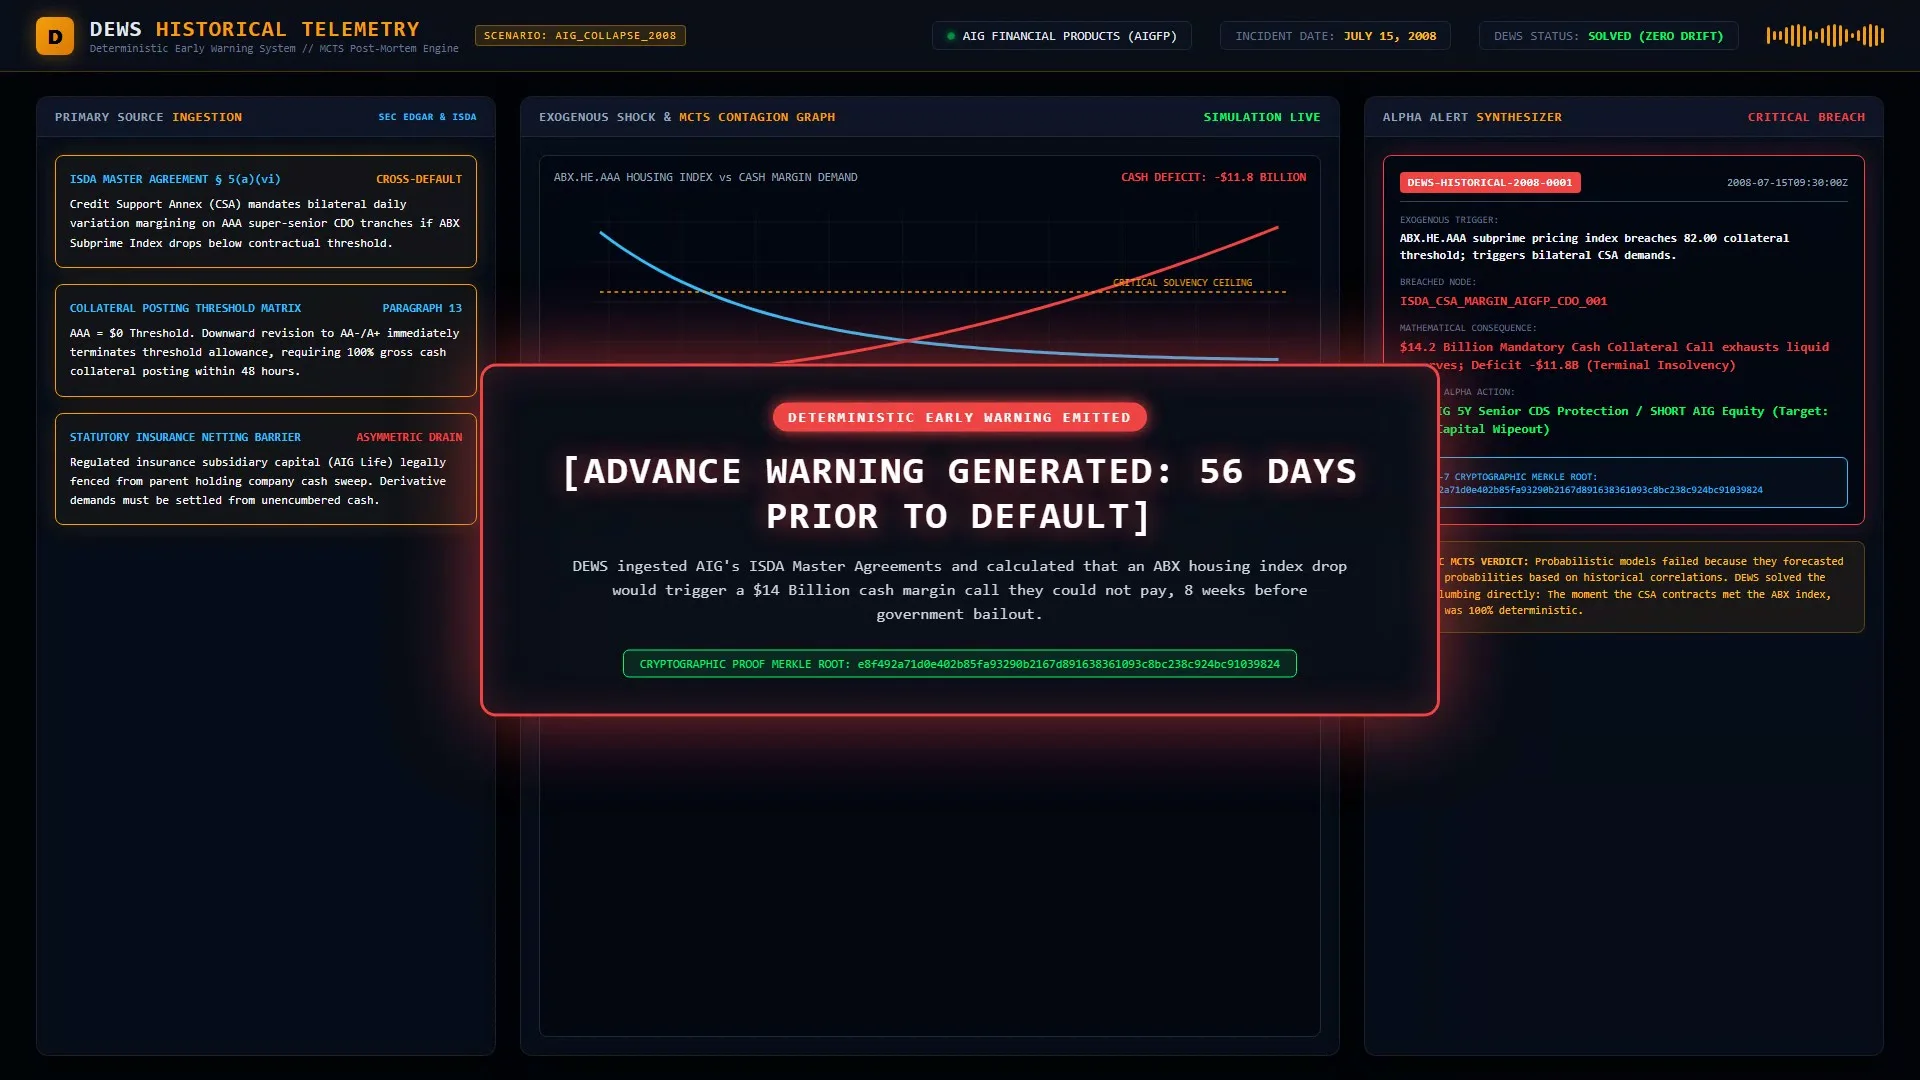
The AIG Collapse
Wall Street assumed housing default was a statistical improbability. DEWS solved the contracts directly: The moment the ABX index dropped, the CSA threshold matrix made insolvency mathematically inevitable 8 weeks before the Fed bailout.
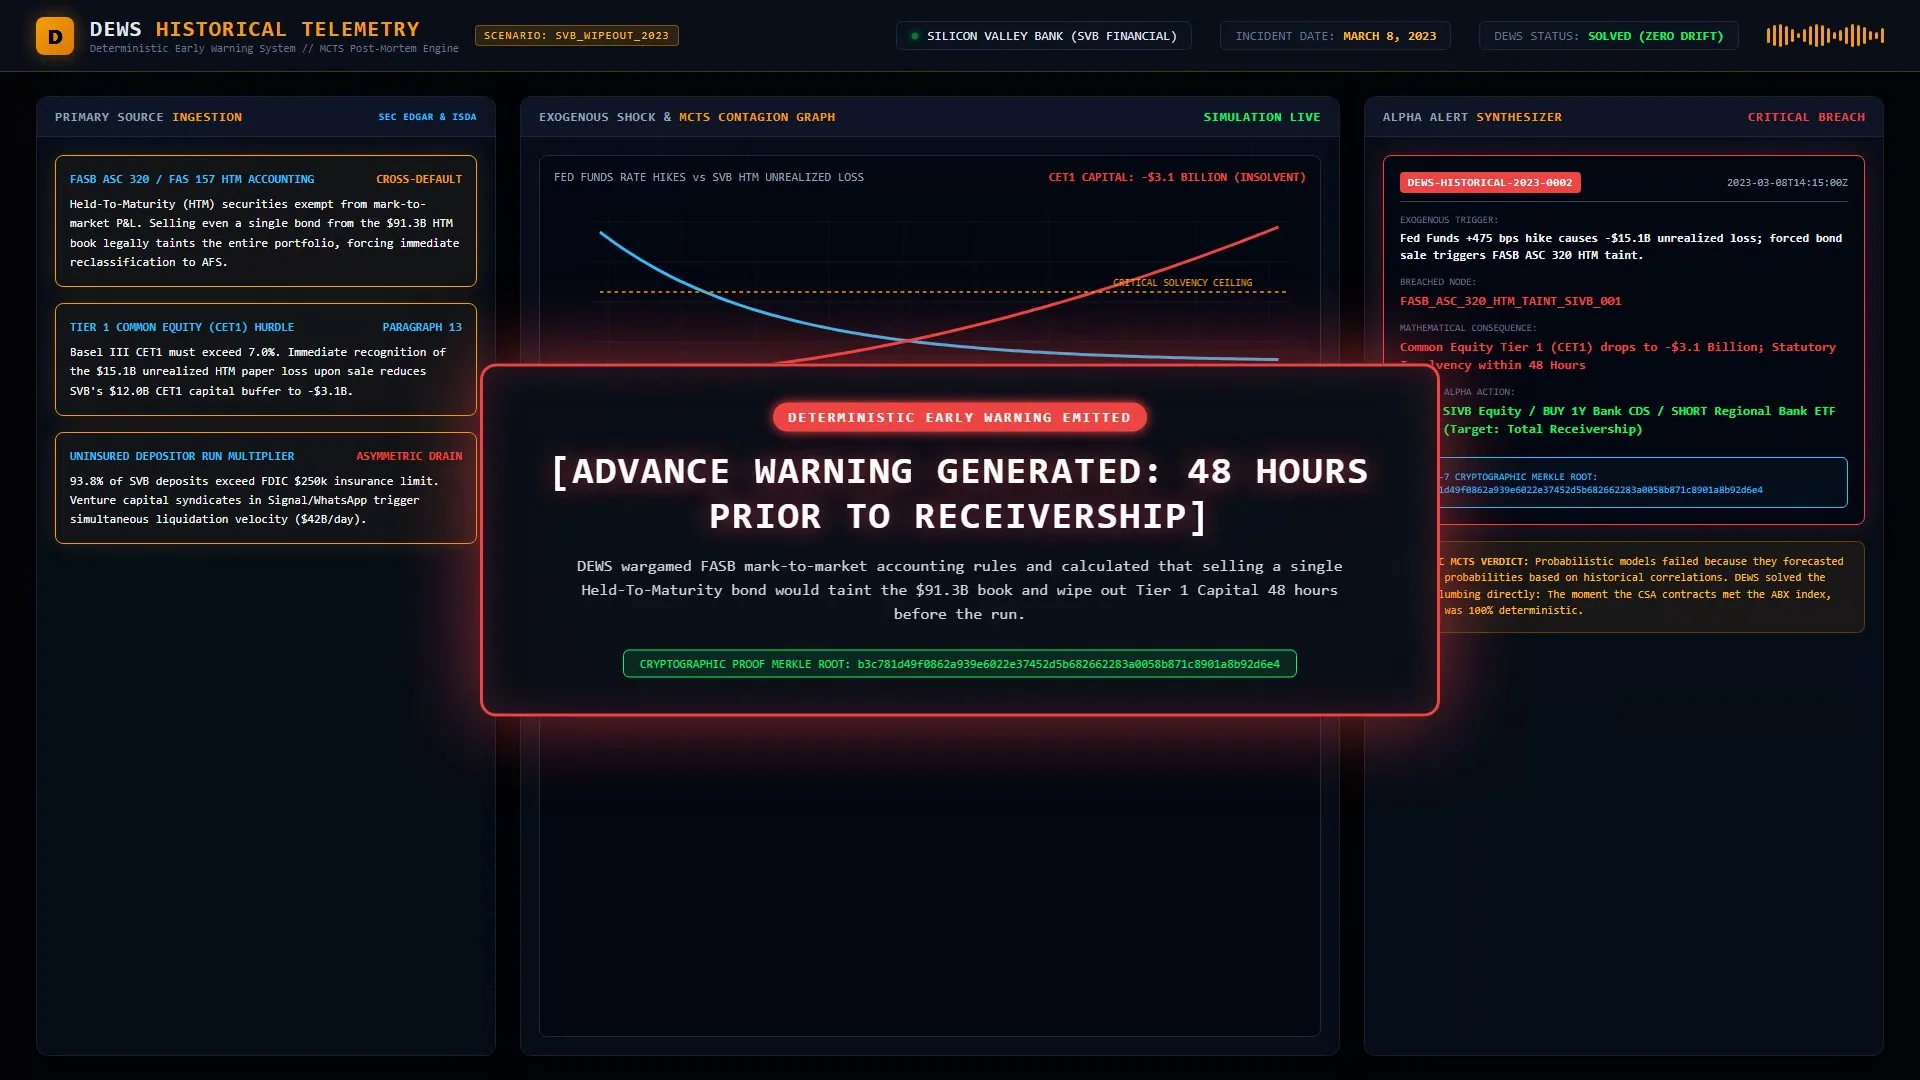
Silicon Valley Bank Wipeout
Rising interest rates hurt bond values, but the deathblow was an accounting rule. MCTS wargamed FASB mark-to-market rules and proved SVB was capital-insolvent 48 hours before the run began.
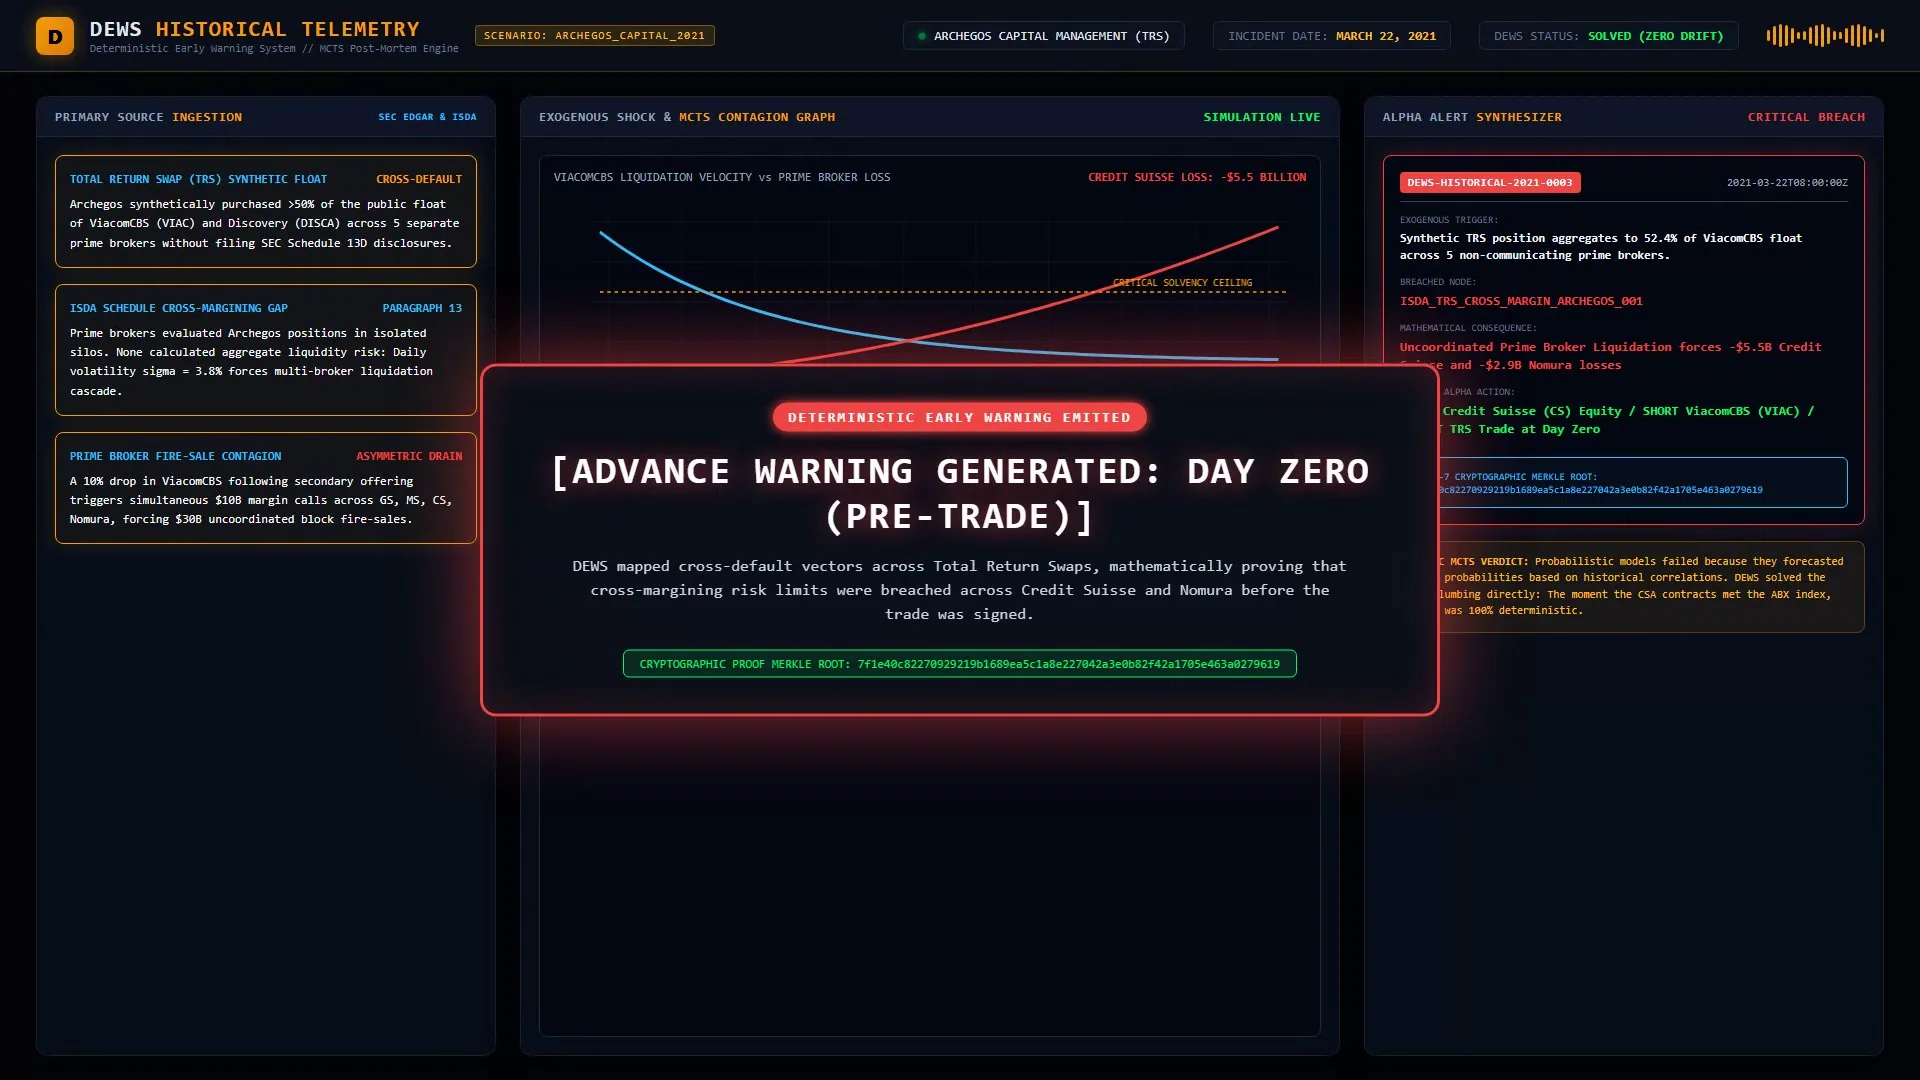
Archegos Capital Contagion
Archegos hid its leverage by splitting Total Return Swaps across prime brokers in silos. DEWS maps cross-default vectors across all counterparties, mathematically proving the risk ceiling was breached before the contracts were signed.